Missouri homeowners · Jackson, Clay, Platte and Cass counties
How to File a Roof Claim in Missouri
What the sequence looks like on the Missouri side of the line, what your policy decides for you, and where homeowners here get tripped up.
Get the roof documented before the phone call
Opening a claim starts a clock and puts a record on your property, so it is worth knowing whether you actually have damage first. Have a roofer walk the roof and photograph it. If there is nothing there, you have spent an hour and you know your roof is fine, which is a real answer and worth having.
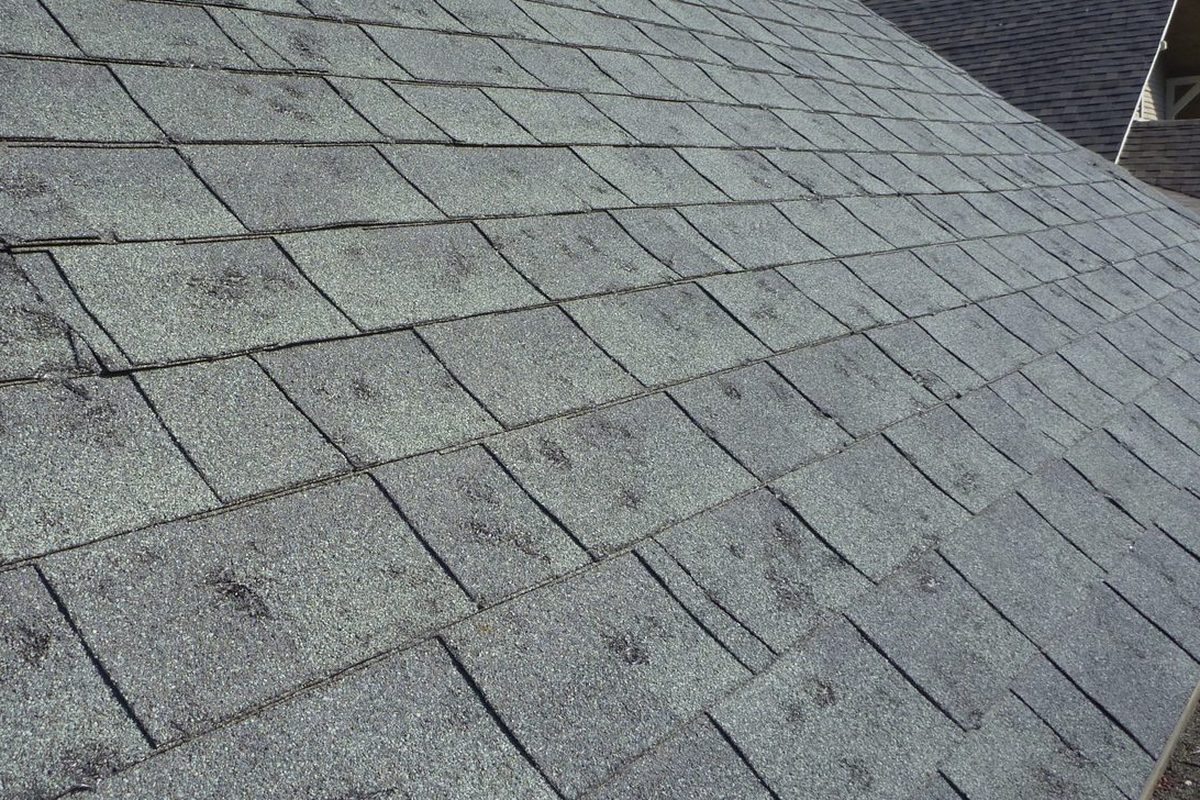
What good documentation looks like: every slope photographed, individual impacts or creases chalked so they show up in the picture, soft metals such as gutters, downspouts and vent hoods shown with their dents, and a date. Interior photos too if there is a stain on a ceiling or a wet spot in the attic insulation.
Keep your own copies. We hand homeowners the whole set regardless of whether they hire us, and that file belongs to you. Photographs taken before anything is cleaned up or tarped are worth more than anything you can produce three weeks later.
Read your declarations page first
The declarations page is the two-page summary at the front of your policy, and it decides most of what happens next. Find your wind and hail deductible, which is often different from the deductible on the rest of the policy and is sometimes a percentage of the dwelling amount rather than a flat number.
Then find out how your roof surface is paid. Some Missouri policies cover the roof at replacement cost. Others pay actual cash value on the roof surface only, or apply a payment schedule that steps the payout down as the roof ages. That single line changes your out-of-pocket by thousands and most people do not know which one they have until they need it.
If you cannot tell what you are reading, call your agent and ask them to say it in plain terms: what is my wind and hail deductible, and is my roof paid at replacement cost or actual cash value. Two questions, and the answers tell you what a claim is going to look like.
The Missouri wrinkle: no state roofing license
Missouri does not issue a statewide roofing contractor license. There is nothing to look up at the state level, which means the filtering that a license board would do in other trades does not happen here. After a hail event that is exactly why the metro fills up with out-of-state crews.
So you verify it yourself. A permanent local address you can find independently, not a PO box and not a truck. Current general liability and workers compensation, confirmed by calling the number on the certificate rather than trusting the paper you were handed. Individual cities do require contractor registration and permits, so ask which jurisdiction your house is in and whether they are registered to pull there.
Do not sign anything that binds you to a contractor before you have a scope and a price in front of you. And if someone offers to cover your deductible, that offer is a problem on its own terms. We do not do it, we will not offer to, and being asked is a reason to end the conversation.
Filing, then the adjuster appointment
Call the claims number on your declarations page or file through the carrier's app. You will need the date of loss, a description of what happened, and what you have found. Ask for the claim number and the adjuster's contact information in the same call, and write both down.
The adjuster will schedule a visit. Get your roofer there for it. This is not about pressure, it is that two people looking at the same slope should be looking at the same items, and a roofer who has already chalked the damage can point at it rather than argue about it. Where an adjuster and a roofer disagree, it is usually about test squares and how far the damage extends, and that is a conversation better had on the roof.
After the visit the carrier issues a scope and an initial payment. Read the scope line by line against what your roofer found. Missing line items happen constantly, and a missing item is a supplement request with documentation attached, not an argument. That request comes from you as the policyholder; a contractor documents, a contractor does not negotiate on your behalf.
Payments, permits and closing the file
If your roof is covered at replacement cost, the first check is the actual cash value, which is the replacement cost minus depreciation and minus your deductible. The held-back amount is recoverable once the work is complete and the final invoice goes in. There is a separate page here that works through that math with round numbers.
Permits are the contractor's job. In this metro that means a different set of rules depending on whether you are in Kansas City proper, Independence, Lee's Summit, Liberty, Blue Springs or an unincorporated pocket of the county, and the inspection that follows is part of the job, not an add-on.
Your out-of-pocket at the end should be your deductible plus anything you chose to upgrade. If the number moved, something changed in the scope, and you should be able to point at the line where it changed. Ask. A contractor who cannot show you that on paper has told you something.
Frequently asked
Do I have to file a claim to get my roof replaced?
Who pays the deductible in Missouri?
The carrier's scope came in lower than my roofer's. What now?
Does Missouri require a licensed roofer for a claim?
How long do I have to file after a storm?
Related pages for Missouri homeowners
Get Your Missouri Roof Documented Before You File
We inspect, photograph and hand you the file. Whether you open a claim is your call.
Have the roof looked at before you call the claims line
Free inspection, photographs you keep, and a written scope you can put next to the carrier's numbers.